
For borrowers considering bad credit truck financing in Las Vegas, the rate and monthly payment depend on the applicant, the truck, and the financing terms. A larger amount financed can mean a higher payment, while the interest rate and repayment period affect the total cost. Applicants with no credit history may face different considerations from those rebuilding or managing challenging credit.
Monthly payments matter, but they do not show the full cost of financing. Consider the amount financed, interest rate, and repayment period together to understand the offer.
Here’s how lenders may assess applications from borrowers with bad or no credit, what can influence rates and payments, and how financing for new and used trucks can differ. We also explain what to review so you can better understand the terms.
Key Takeaways
- Compare the interest rate, amount financed, and loan length together to understand what shapes a truck payment.
- Assess new and used truck options by considering how the vehicle choice affects the amount you need to finance.
- Bad or limited credit doesn’t tell the whole story; lenders may also consider income and other parts of an application.
- Prepare to discuss your income and identification, then explore financing options that fit your credit situation.
- We work with multiple lenders and offer flexible financing options for buyers with no credit, challenging credit, or a credit history they’re rebuilding.
Interest rates and monthly payments
Compare a truck payment by considering the amount financed, interest rate, and repayment period together. Each factor affects both the monthly amount and the total paid over the loan.
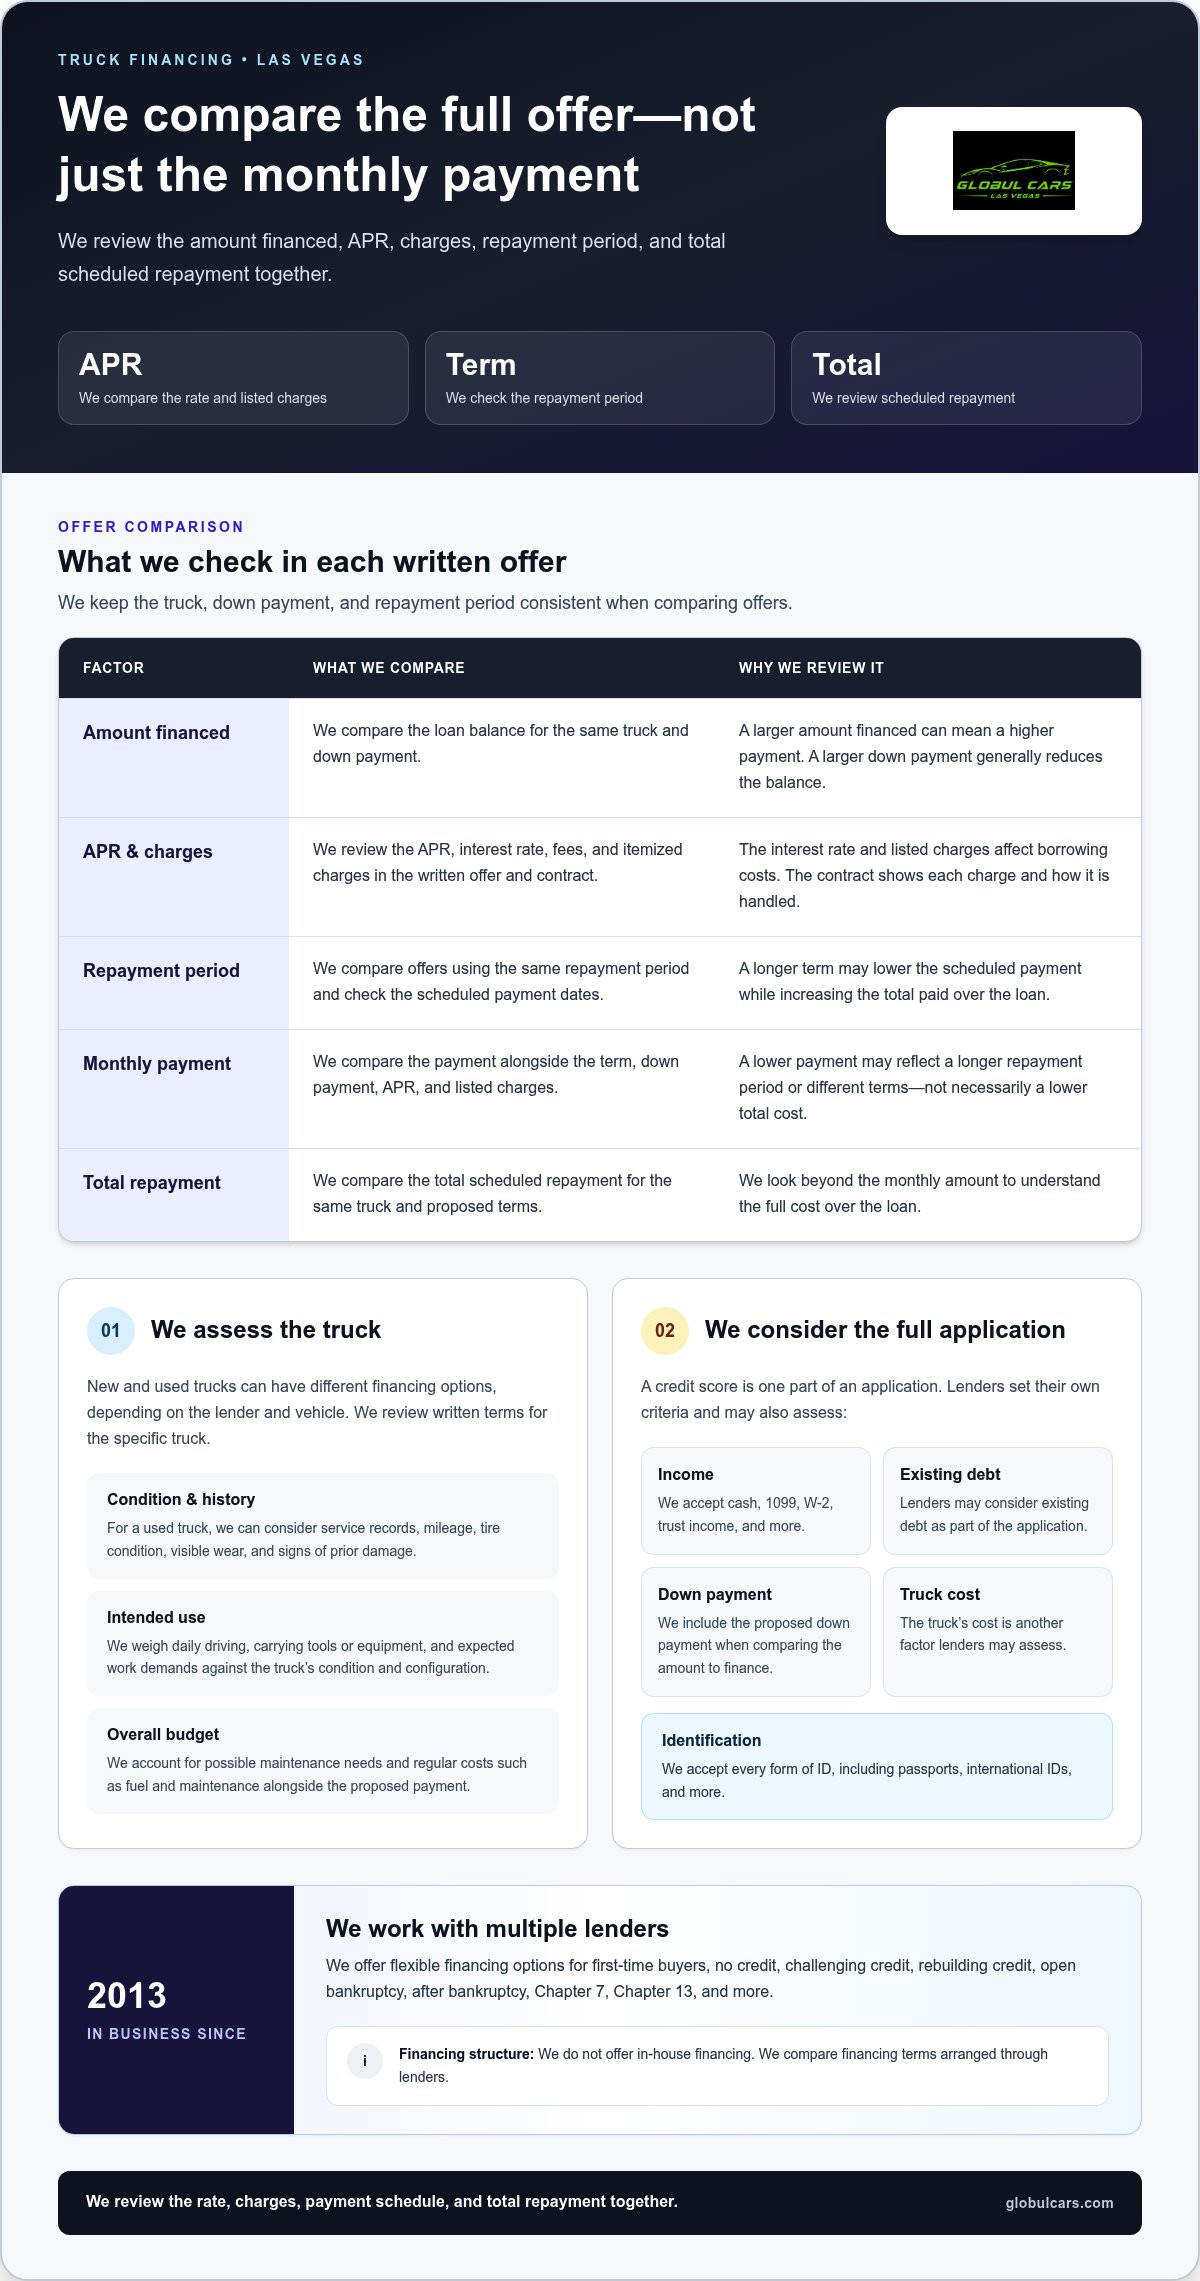
We recommend comparing dealership-arranged financing, banks, and credit unions using written offers for the same truck, down payment, and repayment period. We review each offer’s APR, fees, scheduled payments, and total repayment side by side.
For Nevada loan terms, read the lender’s written rate and charge disclosures alongside the contract. Compare the APR, itemized charges, payment dates, and total scheduled payments because terms can differ by lender and transaction.
Customized Payment Plans
Assess a proposed payment plan by comparing its monthly amount with the repayment period and total interest. A longer term may lower the scheduled payment while increasing the total paid over the loan. Include regular truck costs, such as fuel and maintenance, in your budget before weighing a plan.
Compare offers using the same down payment and repayment period. This helps show whether a lower monthly amount reflects different financing terms or simply a longer loan. Choose a payment you can manage alongside regular household expenses.
Interest Rates and Loan Fees
Review the interest rate and any listed charges because both affect borrowing costs. APR helps compare offers, while the contract shows each charge and how it is handled. Read both before deciding whether one proposal costs less than another.
For example, compare two offers for the same truck and loan amount. If one has a lower monthly payment, check whether it also has a longer repayment period, different charges, or a higher total repayment amount. Looking at all the terms gives a clearer picture than comparing payments alone.
Consider how a down payment changes the amount financed. A larger down payment on the same truck generally reduces the loan balance and may lower payments if the rate and repayment period remain unchanged. Weigh that reduction against keeping funds available for other expenses.
Choose a down payment with your overall budget in mind. Rather than focusing only on reducing the loan balance, account for other ownership costs. When reviewing a proposed payment, identify how the down payment, rate, charges, and repayment period each contribute.
We use these steps to compare an offer:
- We match the truck, down payment, and repayment period across offers.
- We compare APR, fees, monthly payment, and total scheduled repayment.
- We check whether a lower payment reflects a longer repayment period.
- We review payment dates and listed charges in the contract before signing.
New and used vehicle financing
Assess a work truck’s condition and financing terms together. A lower purchase price may reduce the amount financed, but repair needs and suitability for the work matter too. Consider how you plan to use the truck before weighing a loan offer.
Buy-here-pay-here financing means the dealership provides credit directly. Review the contract for the creditor, interest rate, payment schedule, charges, and total repayment. Key risks include taking on payments that strain your budget or overlooking important contract terms.
If in-house financing is a priority, look for used work-truck listings that clearly describe that arrangement. To distinguish direct dealership credit from financing arranged through an outside lender, check who is named as the creditor in the contract.
New and used trucks can have different financing options, depending on the lender and vehicle. For a used truck, we consider its age, condition, mileage, and expected work demands alongside the amount to finance. We compare written terms for the specific truck rather than assuming one financing structure applies to every vehicle.
Used Vehicle Evaluations
We assess a used truck’s condition before focusing on its monthly payment. Our review can include service records, mileage, tire condition, visible wear, and signs of prior damage. A truck suited to commuting may not meet the demands of carrying tools or equipment around Las Vegas.
Build a practical checklist around the work you have in mind. Inspect the cab and bed, test features needed for daily tasks, and compare the vehicle description with what you observe. If the evaluation reveals maintenance needs, include them in your overall budget before choosing a loan amount.
Vehicle Selection
Start with the truck’s intended use: daily driving, carrying equipment, or both. Then compare vehicles by condition, configuration, and amount to finance. A smaller used truck may suit lighter tasks, while heavier work may call for a different vehicle. Match the truck to the job, not appearance alone.
Keep financing comparisons consistent by using the same proposed down payment and repayment period for each truck. Then review the payment and total repayment alongside the vehicle’s condition. This helps distinguish a lower amount financed from a difference caused by loan terms.
We use the truck inventory to compare available options by intended use, condition, and financing structure.
Auto loans for borrowers with bad or no credit
A truck loan application involves more than a credit score. Lenders may assess the full application, including income, existing debt, down payment, and the truck’s cost.
If you have limited credit history in Las Vegas, prepare a clear picture of your monthly finances before choosing a truck. A realistic budget and complete application help show what payment you can manage. When comparing bad credit truck financing Las Vegas options, look beyond your score and consider the full application criteria.
Credit Score Requirements
No single credit score guarantees truck financing in Las Vegas. Each lender sets its own criteria, and a score is only one part of the application. Lenders may also consider income, current debt, credit history, down payment, and the amount requested for the truck.
If you have no established credit history, explain that clearly rather than treating it as a low score. Review your credit report for errors and be prepared to discuss missed payments or other items that may affect how a lender assesses your application. You can also provide context about recent changes in income or expenses when applying for bad credit truck financing in Las Vegas.
Think of the application as a set of connected details. For example, the same credit profile may be assessed differently when paired with steady income and a smaller loan request. The truck’s price, your down payment, and the proposed repayment period can all affect the amount being evaluated.
Improving Approval Chances
Before applying, organize income records, identification, and details about your regular expenses. Use consistent information throughout the application, and include every income source you want considered. Clear records help explain your ability to make the proposed payments.
Choose a truck that fits your budget rather than starting with the largest loan you might qualify for. A lower amount financed can make the requested payment more manageable. If you have savings available, compare how different down payments change the amount borrowed while leaving funds for routine expenses.
Use these practical steps before submitting an application:
- Review your credit report and correct inaccurate personal or account information.
- Gather recent income records and make a list of recurring monthly obligations.
- Set a payment limit using your actual take-home income and household costs.
- Compare trucks by condition, intended use, and amount you need to finance.
- Read each proposed loan’s rate, payment schedule, and fees before agreeing.
First-time borrowers can prepare a simple budget showing income and recurring expenses. List housing, utilities, insurance, and existing loan payments before deciding what remains for a truck payment. This helps identify a loan amount that fits your finances instead of relying on a lender’s maximum offer.
Apply with accurate details and keep a copy of the terms you review. If an offer changes the payment period or down payment, compare the revised total repayment and scheduled payments with your original budget before deciding.
Bad-credit and no-credit financing
Prepare identification, income records, and details about your expenses for a truck loan application. Do not assume there will be no credit check or that a cosigner is unnecessary. Lenders set their own application requirements and may review credit history. When comparing bad credit truck financing Las Vegas options, understand what information each lender considers.
Required Financing Documents
Gather a photo ID, proof of income, and information about your current expenses. Income records can include pay stubs, tax documents, or statements that show other income sources. We accept all types of income: cash, 1099, W-2, trust income, etc. We accept every form of ID: passport, international IDs, and more.
Keep your application details consistent. For example, use the same income figures on your application and supporting records, and bring documents that explain any differences. A lender may also ask about housing costs, existing payments, or the truck you plan to finance, since those details help assess the proposed loan.
Dealership Financing Options
Dealership-arranged financing may involve the dealer arranging a loan through a lender, while in-house financing means the dealer provides the credit directly. These are different arrangements. Check who will be listed as the creditor and review the written agreement for the rate, payment schedule, charges, and total repayment.
If a dealership submits an application to multiple lenders, the available terms may depend on each lender’s criteria. Compare written offers for the same truck and amount financed. Focus on the full loan terms, not simply whether an application is accepted. This gives Las Vegas borrowers a clearer basis for comparing financing structures.
No-Credit-Check and Cosigner Options
A no-credit-check claim does not explain how a lender evaluates repayment ability. A lender may consider income, expenses, down payment, and vehicle details, while credit review can vary by financing arrangement. Read the application and contract to understand what information is used and who makes the lending decision.
A cosigner is not a universal requirement for every truck loan. If a lender allows an application without one, the borrower’s income, expenses, and other application details still matter. If a cosigner is proposed, both people should understand that the agreement may make the cosigner responsible for payments under its terms. These details also matter when weighing bad credit truck financing Las Vegas offers.
Before applying in Las Vegas, organize identification, income records, and a list of recurring expenses. Add the truck’s details once you have chosen a vehicle. This makes it easier to compare lender requests and offers without overlooking a key term.
Which Las Vegas truck dealerships offer financing for buyers with bad credit?
In Las Vegas, look for dealerships that clearly describe their financing options for buyers with bad or limited credit. Some arrange financing through outside lenders, while others may use different arrangements. This distinction affects who makes the lending decision and who appears as the creditor in your contract.
Start by identifying the financing structure rather than relying on a broad “all credit” phrase. Ask whether the dealership submits applications to multiple lenders or provides financing directly. A dealership working with multiple lenders may present options based on different lender criteria, while direct financing follows the dealership’s own terms.
Read the written offer for the truck you are considering. Check the creditor’s name, interest rate, APR, listed charges, payment schedule, and total repayment. Two offers for the same truck may have different payments because their rates or repayment periods differ. Compare the complete terms, not just the amount due each month.
Use these details to understand a Las Vegas dealership’s financing offer:
- Applicant criteria: Does the application allow buyers with bad credit, no credit, or a limited credit history?
- Lending arrangement: Is the loan arranged through lenders, or provided directly by the dealership?
- Written terms: Are the creditor, APR, fees, and payment schedule clear in the agreement?
- Vehicle fit: Does the truck’s condition and intended use match your work needs?
A dealership’s financing process can affect the application steps. For example, an application routed to lenders may involve lender-specific decisions and terms, while direct financing may use a different approval process. In either case, review the loan documents to understand who makes the credit decision and where payments go.
Before selecting a truck, match the financing offer to your budget and the vehicle’s purpose. A work truck used to carry equipment has different practical needs from one used mainly for commuting. Compare the truck’s condition, amount financed, and scheduled payments together so the financing supports how you plan to use the vehicle.
In Las Vegas, a dealership that works with multiple lenders may serve borrowers with different credit histories, but each lender can assess applications differently. Keep your income and application details consistent, and read every proposed term before agreeing. If an offer changes, compare the revised payment schedule and total repayment with the earlier version.
Use the contract as your final reference. Confirm that the listed creditor, amount financed, APR, charges, due dates, and payment schedule match the terms you accepted. This helps you understand the financing arrangement before taking the truck home.
Look for Las Vegas dealerships that provide financing directly rather than arranging loans through outside lenders. Ask whether they have used work trucks and review the written offer to confirm the creditor and terms.
Globul Cars: Vehicle Financing Solutions
Globul Cars offers Vehicle Financing Solutions for buyers exploring financing with challenging credit or no credit. We work with multiple lenders and offer flexible financing options for first-time buyers, no credit, challenging credit, rebuilding credit, open bankruptcy, after bankruptcy, Chapter 7, Chapter 13, and more. We don’t provide in-house financing; lender terms depend on the application and vehicle.
Bring your financing questions and the terms you are weighing when comparing a truck loan. We can help you understand the available options alongside your vehicle choice. Our pre-owned selection includes Mercedes-Benz, BMW, and Land Rover vehicles.
Contact Globul Cars to discuss your financing needs and next steps.
Take the Next Step Toward a Truck That Fits
Your next step is to match the truck you need with a payment that works in your everyday budget. Before moving ahead, decide how you will use the vehicle and what monthly amount leaves room for other expenses. That gives you a practical starting point for discussing financing, rather than choosing a truck based only on its features.
If you are exploring bad credit truck financing in Las Vegas, bring your questions about the application and financing terms. We can discuss Vehicle Financing Solutions and help you consider your options. Start with your needs, your budget, and the vehicle you have in mind.
Contact Globul Cars about financing to take the next step. A clear plan can help you move forward with confidence.
Frequently Asked Questions
Looking for a Bad Credit Car Dealer in Las Vegas?
Globul Cars is a used-vehicle dealership in Las Vegas offering Vehicle Financing Solutions for buyers across credit types. Its inventory includes cars, trucks, and pickups. Start by identifying the vehicle you need, then discuss financing options for that choice. Globul Cars works with multiple lenders rather than providing financing in-house, so review the lender and terms named in any offer before deciding.
What down payment is typically required for bad credit truck financing in Las Vegas?
There is no single down payment amount that applies to every truck loan. It depends on the truck’s purchase price, the amount financed, and the lender’s assessment of your application. Compare how a smaller or larger down payment changes the loan balance and your available savings. Keep funds for regular expenses, and judge the offer by its full repayment terms, not the down payment alone.
What are average APRs and loan terms for bad credit truck loans in Nevada?
A single average APR or loan term will not tell you what a specific borrower may be offered in Nevada. Lenders set terms using factors such as credit history, income, the truck, and the amount financed. Compare written offers for the same vehicle and down payment. Review each APR, repayment period, scheduled payment, and total repayment to see how the terms differ.
Are there Nevada laws or lender rules for truck loan interest rates and fees?
Terms can differ by lender and transaction. Compare the lender’s written APR and charge disclosures with the contract, including itemized charges, payment dates, and total scheduled payments.
Where can I find used work trucks with in-house financing in Las Vegas?
When comparing used work trucks in Las Vegas, check whether financing is provided directly by the dealership or arranged through an outside lender. Review the contract to confirm who is named as the creditor.


