
What if the dealership selling the car is also the company financing it and collecting your payments? That’s the key distinction behind what is a buy here pay here loan. It describes a financing model where the dealership provides the loan directly, rather than arranging financing through outside lenders. If you’re comparing options in Las Vegas, start by identifying who will lend you the money, who will receive your payments, and what you’ll repay over the full loan term.
We know that credit history and financing details can make car shopping feel complicated. In this article, we explain how buy here pay here financing works, how it differs from financing through an outside lender, and which details to review before signing. At Globul Cars, we work with multiple lenders and offer flexible financing options, not in-house financing. We work with first-time buyers and people with no credit, challenging or rebuilding credit, open or past bankruptcy, Chapter 7, Chapter 13, and more. We accept all types of income, including cash, 1099, W-2, and trust income, as well as every form of ID, including passports and international IDs.
Key Takeaways
- Understanding what is a buy here pay here loan starts with identifying who provides the financing and receives your payments.
- The application process and required documents depend on the financing arrangement. Review each step and its requirements.
- Compare the financing source, payment recipient, and agreement details to see how dealership financing differs from an outside lender.
- Before signing, read the written terms, payment dates, total repayment obligation, and the agreement’s stated consequences and options.
What Is a Buy Here Pay Here Loan, and Who Provides It?
If you’re asking what is a buy here pay here loan, focus on the financing relationship: a dealership typically arranges financing and handles payments directly. In a traditional buy here pay here arrangement, the dealer often provides the credit and receives payments. The lender, payment process, and contract terms can vary, so the label alone doesn’t tell you every detail.
Buy here pay here describes a vehicle-financing arrangement in which the dealership typically provides financing and collects payments, while the signed agreement identifies the actual lender and payment terms.
The loan and the vehicle purchase are related, but they aren’t the same thing. The vehicle is what you’re buying; the loan is the agreement to repay money borrowed for the purchase. You’ll review a purchase contract for the vehicle and financing documents that describe the credit arrangement. Read the paperwork as a whole so you understand what you’re buying, who is financing it, and where payments go.
What do “buy here” and “pay here” mean?
“Buy here” points to purchasing a vehicle through the dealership. “Pay here” refers to making loan payments through that dealership in the typical model. The dealer may serve as both the financing source and payment collector, but those roles aren’t universal. The signed agreement explains the specific arrangement, including who receives payments and how to make them. For additional background, see What is a Buy Here Pay Here Loan?
Is buy here pay here the same as dealership financing?
Not necessarily. “Dealership financing” can also mean the dealership helps arrange a loan from a separate lender. In that case, the outside lender provides the financing, and the agreement identifies where payments are made. With direct dealer financing, the dealership typically provides the loan and collects payments. Two buyers shopping at dealerships could sign similar vehicle purchase contracts but have different lenders and payment recipients. Neither structure is automatically better; the written terms show what each arrangement means for you.
That distinction matters because the dealership you visit isn’t always the company lending you money. Look for the lender’s name in the financing documents, then match it to the payment instructions. Read the agreement carefully before signing. The contract, not the label used in conversation or advertising, spells out the arrangement you’re accepting.
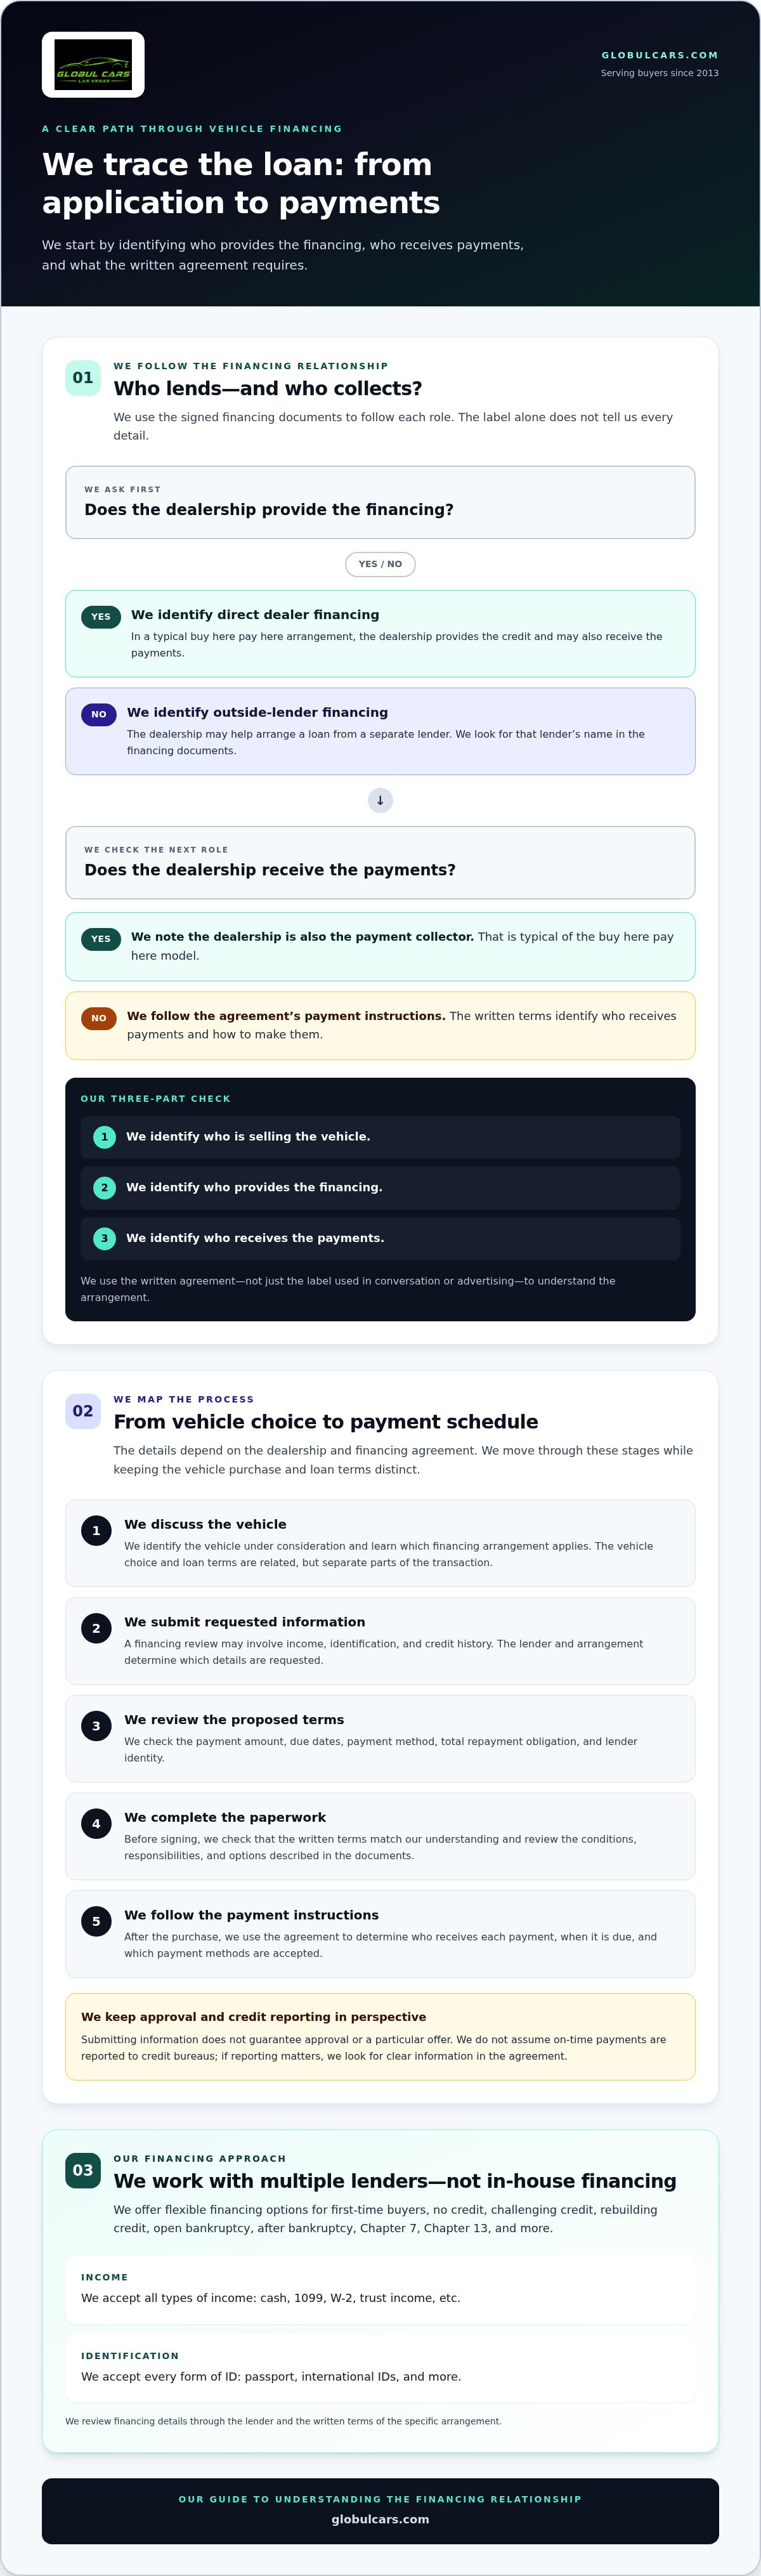
We find it helpful to separate three questions as you review the paperwork: Who is selling the vehicle? Who is providing the financing? Who receives the payments? The answers may point to one business or to separate parties. Knowing the difference gives you a clearer starting point for comparing the vehicle purchase contract with the loan terms and understanding how the financing relationship works.
How Does a Buy Here Pay Here Loan Work From Application to Payments?
The details depend on the dealership and financing agreement, but the process generally moves from choosing a vehicle to reviewing loan terms and following a payment schedule. To understand what is a buy here pay here loan in practical terms, pay attention to each stage, especially who makes the financing decision and where payments must go.
- Discuss the vehicle. Identify the vehicle you’re considering and learn which financing arrangement applies to the purchase. The vehicle choice and loan terms are related, but they’re separate parts of the transaction.
- Submit requested information. A financing review may involve information about your income, identification, and credit history. The requested details depend on the lender and arrangement.
- Review the proposed terms. If financing is offered, read the agreement carefully. Check the payment amount, due dates, payment method, total repayment obligation, and lender identity.
- Complete the paperwork. Before signing, make sure the written terms match your understanding of the financing. Review the conditions, responsibilities, and options described in the documents.
- Follow the payment instructions. After the purchase, use the agreement to determine who receives each payment, when it is due, and which payment methods are accepted.
What happens during a buy here pay here application?
Buyers provide information requested for a financing review. Depending on the arrangement, that may include income, identification, and credit details. Approval criteria and documentation can differ, so submitting information doesn’t guarantee approval or a particular offer. Before accepting, compare the proposed terms with your budget and read the documents closely. The Consumer Financial Protection Bureau offers a consumer overview of buy here pay here loans, including points to consider about this type of financing.
How are payments handled after the vehicle purchase?
The payment recipient and accepted methods depend on the signed agreement. Find the payment instructions and due dates in the contract, then keep them accessible so you know where and when to pay. Don’t assume every dealership handles payments the same way or that on-time payments are reported to credit bureaus. If reporting matters to you, look for clear information about it in the agreement.
Buyers considering a used vehicle in Las Vegas can begin exploring financing through our online financing application.
Buy Here Pay Here vs. Outside-Lender Financing: What Is Different?
Knowing what is a buy here pay here loan helps you tell the difference between direct dealer financing and a loan arranged through a separate lender. The main distinction is who provides the credit and receives your payments. Other terms, including rates, eligibility, down payment, and payment schedules, depend on the specific offer and agreement. Neither structure is automatically the better choice for every buyer.
| What to compare | Buy here pay here | Outside-lender financing |
|---|---|---|
| Financing source | The dealership typically provides the financing directly. | A separate lender provides the loan, often arranged through the dealership. |
| Payment recipient | Payments are typically handled by the dealership. | Payments go to the lender or as specified in the agreement. |
| Agreement details | The documents describe the dealer-financing terms and payment process. | The documents identify the lender and set out the loan and payment terms. |
Who provides the financing and receives payments?
In a typical buy here pay here arrangement, the dealership both provides financing and collects payments. With outside-lender financing, the dealership may help arrange a loan, but a separate lender provides it. Read the agreement rather than relying on the financing label: find the lender’s name and the payment instructions. The parties involved can affect where you direct questions and payments.
For example, imagine two people buying similar used vehicles. One signs an agreement with direct dealer financing; the other receives a loan from a separate lender arranged through the dealership. The vehicle purchase may look similar, but the financing source and payment recipient differ. Our vehicle financing solutions guide offers broader context on financing options in Las Vegas.
What should borrowers compare between financing options?
Look beyond whether an application is approved or how quickly a decision arrives. Compare the written terms and consider how the scheduled payments fit your income timing and regular expenses. A payment plan that looks manageable on paper still needs to work with your budget. Review all stated fees and the total amount you’re expected to repay before deciding.
We recommend lining up the agreements side by side if you have more than one offer. Compare:
- The full repayment obligation, including any stated fees.
- The payment amount, due dates, and accepted payment methods.
- The lender’s identity and instructions for making payments.
- Any conditions, responsibilities, or options described in the agreement.
Then consider the whole arrangement, not just one appealing detail. Approval speed or a financing path that accommodates your credit history may matter, but neither replaces a careful review of the payment schedule and total obligation. The written agreement is the clearest basis for comparing what you’ll owe and how you’ll repay it.
What Should You Review Before Accepting a Buy Here Pay Here Loan?
Before accepting financing, take time to understand the full written agreement, not just the payment amount. We encourage buyers to read each term carefully and make sure they understand the responsibilities and options described before signing. Approval and proposed terms depend on the financing review.
Which loan terms should you read closely?
Start with the figures and timing recorded in the agreement. Look for the amount financed, payment schedule, and total amount due where disclosed. Then read the sections about late payments, stated fees, and other consequences. Those details shape your obligations, so rely on the written terms rather than a verbal summary.
Use this checklist as you review the documents:
- Amount financed: Confirm the amount you’re borrowing and how it relates to the vehicle purchase.
- Payment schedule: Find each payment amount, due date, and the instructions for submitting payments.
- Total repayment obligation: Review the total amount due where it’s disclosed, along with any stated fees.
- Late-payment terms: Read exactly what the agreement says about missed or late payments and any related consequences.
- Options and conditions: Understand any choices, requirements, or steps described in the contract.
If a phrase is unclear, ask for an explanation before signing. A careful review is a practical step, not a delay. Make sure you understand what the contract says about your responsibilities and what options it describes if circumstances change. Keep a copy of the final documents so you can refer back to the terms.
How can you assess whether payments fit your budget?
Compare the scheduled payments with reliable income and recurring household expenses. Consider when income arrives and when other bills are due, so you can judge whether the payment timing is workable. We also recommend accounting separately for vehicle ownership expenses, such as fuel, insurance, and maintenance, rather than treating the loan payment as the full cost of having a car.
A payment that seems manageable each month doesn’t automatically make the full obligation affordable. Review the total repayment amount and the length and frequency of payments stated in the agreement, then consider how those commitments fit alongside your other expenses. Don’t base your decision only on whether financing is offered or how quickly you receive a decision. The written terms and your budget both matter.
For additional perspective on evaluating a vehicle as you shop, our independent car lot buying guide offers related guidance. If you’re ready to explore used vehicles in Las Vegas, browse our available cars as you consider your financing and budget.
How Globul Cars Helps Las Vegas Buyers Explore Vehicle Financing
For Las Vegas buyers, vehicle shopping and financing are connected decisions. We help make the process easier to approach by helping you consider the kind of used vehicle you need and the payment you can reasonably plan for. Start with practical priorities, such as space, everyday use, or a truck for work or other needs, then consider how your vehicle choice fits your overall budget.
What financing situations do we work with?
We work with multiple lenders and offer flexible financing options for first-time buyers and people with no credit, challenging credit, or rebuilding credit. We also work with buyers with open bankruptcy, after bankruptcy, Chapter 7, Chapter 13, and more. We accept all types of income, including cash, 1099, W-2, and trust income, as well as every form of ID, including passports and international IDs. Our financing is arranged through lenders, not through in-house financing. Review the proposed agreement to understand the terms for your purchase.
What is a practical next step for a Las Vegas buyer?
Begin by deciding what you need from your next vehicle and setting a budget that accounts for more than the loan payment. A clear starting point can help narrow your search and make it easier to compare vehicles on practical details, not just appearance. Browse our used vehicle inventory as you consider which options may suit your plans.
Once you have a vehicle or budget in mind, you can begin the online financing process. We invite you to take that step when you’re ready and review the details at a pace that feels comfortable. We’re here to help you explore used vehicles and financing in Las Vegas.
Move Forward With a Clear Financing Plan
Understanding what is a buy here pay here loan can help you approach your next vehicle decision with clearer expectations. Give yourself time to consider how your vehicle needs, budget, and financing choices fit together. A confident decision doesn’t have to be rushed. It starts with knowing what matters most to you and taking the next step at a manageable pace.
As you plan, think about how you’ll use your vehicle, what you can comfortably afford, and which details you want to understand before agreeing to financing. Those priorities can help guide your search and make it easier to focus on options that suit your circumstances. We’re here to help you explore vehicle financing as you consider your next car in Las Vegas.
Explore our vehicle financing options and take the next step toward finding a vehicle that fits your plans. We look forward to helping you move ahead with care and confidence.
Frequently Asked Questions
Is a buy here pay here loan the same as a regular car loan?
We distinguish these loans by looking at who provides the financing and handles payments. In a typical buy here pay here arrangement, the dealership takes on those roles; another auto loan may come from a separate lender. For example, a dealership can arrange financing with an outside lender. Compare the actual agreement terms and payment instructions, since the loan label alone doesn’t explain the full arrangement.
Do buy here pay here dealerships check your credit?
Some may review credit history, while others may use different approval criteria. “Buy here pay here” doesn’t necessarily mean there’s no credit review. We recommend providing accurate information with an application and reading the proposed terms carefully. The financing documents identify the lender and explain the terms being offered for that specific purchase.
Can you get a buy here pay here loan with no credit?
It may be possible, but no credit history doesn’t guarantee approval. We encourage buyers to treat an application as a review, not a promise of financing or particular terms. Before applying, consider the vehicle you need and the payment your budget may support. If an offer is made, compare its schedule and total repayment obligation with your other expenses before deciding whether it works for you.
Do buy here pay here payments build credit?
Not necessarily. Whether payments are reported to credit bureaus depends on the lender’s practices and the agreement. Look for clear written information about reporting before signing, rather than assuming on-time payments will build a credit history. Keep personal records of due dates and payments, too, so you can track your loan even if reporting isn’t part of the arrangement.
What happens if you miss a buy here pay here payment?
The result depends on the terms in your contract. Read the section about late or missed payments so you understand the stated consequences and any available options. If you expect a payment may be late, follow the instructions in your agreement and keep a record of any related communication. The process can differ between financing arrangements.
Can you pay off a buy here pay here loan early?
Whether and how you can pay off a loan early depends on the agreement. Review its payoff terms before sending extra money, including how the remaining amount is calculated and whether any conditions apply. Use the payoff instructions in your documents and keep written confirmation with your loan records for future reference.


