
What if a stronger car loan application starts with choosing a realistic vehicle budget, not just focusing on your credit score? It’s understandable to feel unsure about what lenders will consider, especially if you have limited credit history, challenging credit, or income that doesn’t fit a standard pay stub. Learning how to improve chances of car loan approval means preparing a clear application and understanding what you can comfortably afford, not expecting approval to be guaranteed.
We’ll walk through practical steps to organize your information, set a budget, and compare financing options. We’ll also explain how income, credit background, and vehicle choice can factor into an application, so you can approach the process with a clearer plan.
At Globul Cars, we help Las Vegas buyers explore vehicle financing through a straightforward process. We’ll explain what information to prepare, how to think through your vehicle budget, and what to keep in mind as you consider your next step.
Key Takeaways
- To learn how to improve chances of car loan approval, prepare accurate, consistent application details. No step guarantees a lender’s decision.
- Review your credit, income information, and existing financial obligations before applying so you can present a clear picture.
- Set a vehicle budget around your household priorities, and compare different requested amounts as a planning exercise, not a prediction of approval.
- A credit challenge or limited credit history doesn’t automatically determine every application outcome. The lender reviews the full application and makes the financing decision.
- We guide Las Vegas buyers through a practical sequence: set a budget, prepare information, submit an application, and review available financing options.
How to Improve Your Chances of Car Loan Approval: What Lenders May Consider
Preparing carefully can make your application clearer, but no checklist or single action guarantees that a lender will approve financing. Lenders may consider your credit history, income, existing financial commitments, and the amount you’re asking to finance. The weight given to each factor can vary. It helps to understand how they fit together rather than assume one number tells the whole story.
Application readiness means presenting an accurate picture of your finances. The lending decision remains with the lender. That distinction matters when you’re working out how to improve chances of car loan approval. You can prepare thoughtfully and choose a reasonable request, but the result depends on the lender’s review of your full application.
Which parts of a car loan application can affect a decision?
Credit history is one consideration, not a complete summary of your finances or your ability to manage a payment. A lender may review your past borrowing alongside your current income and financial commitments. Those existing obligations help put a proposed vehicle payment into context, so consider the full budget rather than looking at a car loan in isolation.
The amount requested is part of that picture, too. A vehicle choice that calls for more financing may create a different application than a lower amount, but comparing the two won’t predict an outcome. In general terms, car finance can involve different arrangements, so treat the requested amount as one element of the financing being considered.
Why approval requirements can vary between lenders
Lenders may use different review criteria and offer different financing programs. A particular credit score or income level shouldn’t be treated as a universal approval rule. One lender’s decision also doesn’t establish what every other lender will decide. Each lender reviews the application under its own approach and makes its own decision.
Keep this variation in mind as you learn about vehicle financing options in Las Vegas. Comparing options can help you understand the process, but it can’t tell you in advance what decision a lender will make. Focus on presenting your circumstances accurately, then consider any financing terms in light of your budget and needs.
Separate what you can control from what you can’t. You can provide accurate information, account for your existing commitments, and think carefully about how much financing to request. You can’t set a lender’s criteria or know the decision in advance. This keeps expectations realistic while you prepare and review available options.
Prepare Your Credit, Income, and Application Before You Apply
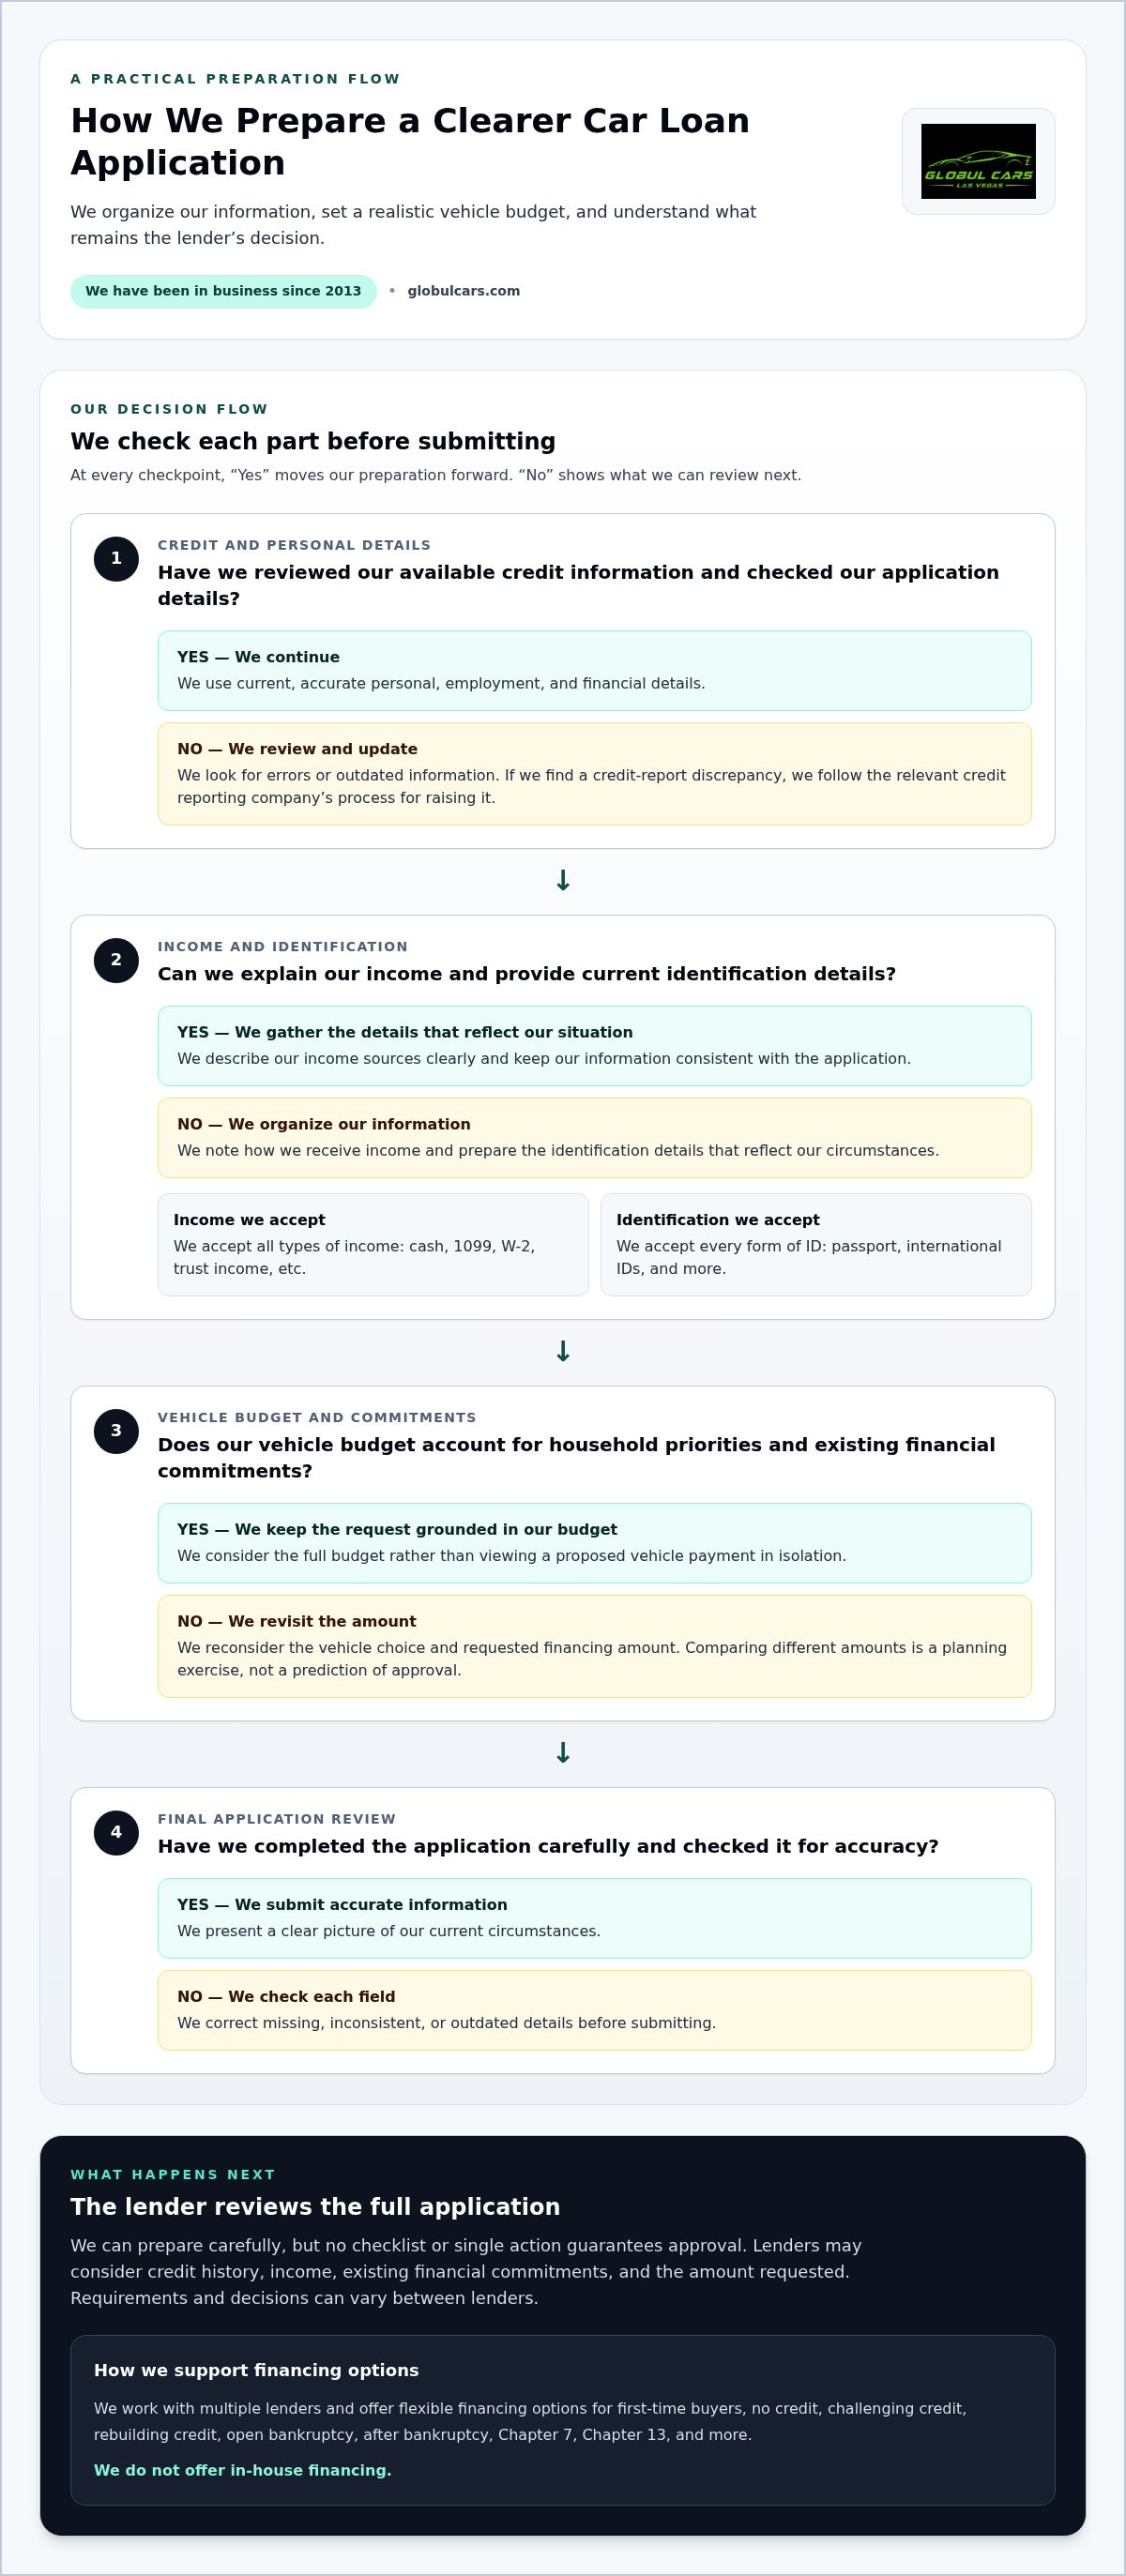
Preparation can help you catch missing or inconsistent details before submitting an application. It won’t guarantee a lending decision, but it gives you a clearer view of the information you’re providing. If you’re considering how to improve chances of car loan approval, follow a practical order: review your information, gather income and identification details, set a budget, then apply.
Review your credit and correct application details
Before applying, review the credit information available to you so you can understand what it says and spot details that may need attention. If you find a discrepancy, follow the relevant credit reporting company’s process for raising it. Reviewing your information doesn’t guarantee a score change, but it can help you identify details you may want to address before completing an application.
Check that your personal, employment, and financial details are accurate and consistent throughout the application. Use information that reflects your current circumstances. Before submitting, review each field rather than rushing through it. If something has changed, enter your current details instead of relying on an older application or record.
Organize income and identification information
Think through how you receive income and how to describe it clearly. You may receive W-2 wages, 1099 income, cash income, trust income, or income from another source. Gather the information that reflects your circumstances so you can give an accurate account instead of assuming every applicant has the same paperwork.
We accept all types of income, including cash, 1099, W-2, trust income, and more. We also accept every form of ID, including passports and international IDs. Make sure the details you provide are current and consistent with your application. If you have income from more than one source or don’t receive a typical pay stub, be ready to explain your situation clearly.
Use this preparation checklist:
- Review your credit and personal information for errors or outdated details.
- Gather income and identification information that reflects your situation.
- Set a vehicle budget based on your household commitments and priorities.
- Complete the application carefully, then review it for accuracy before submitting.
This sequence keeps the process manageable without treating approval as a sure thing. Clear, consistent details help you explain your circumstances, while a realistic budget gives context to the amount you request. When you’re ready, explore financing options with us.
Credit Challenges, No Credit, and Bankruptcy: Practical Ways to Approach an Application
A credit setback can make applying feel discouraging, but one issue doesn’t automatically determine every application outcome. A first-time buyer with little credit history has a different background from someone rebuilding credit after missed payments. Neither circumstance alone tells you what a lender will decide. The lender reviews the application, and the outcome depends on its details and the lender’s criteria.
Credit history is one part of an application, not the whole picture a lender reviews. That’s a helpful distinction as you consider how to improve chances of car loan approval. Preparation can help you present your circumstances clearly, but it can’t promise approval, a particular rate, or specific terms.
Applying with limited, rebuilding, or challenging credit
If you’re a first-time buyer, have no credit, or are working to rebuild your credit, focus on giving a clear and accurate account of your situation. Don’t hide past challenges or guess at details. A complete, honest application lets the lender consider the information presented without avoidable omissions or inconsistencies.
We work with multiple lenders and offer flexible financing options for first-time buyers and people with no credit, challenging credit, or rebuilding credit. Each lender makes its own financing decision, so no credit background guarantees qualification or particular terms.
What to know when bankruptcy is part of your history
Bankruptcy circumstances can vary. You may have an open bankruptcy or a bankruptcy in your past, including Chapter 7 or Chapter 13. We offer flexible financing options for applicants in these situations, but a label alone can’t predict a lender’s decision. The application and the lender’s review determine the outcome.
Share your circumstances accurately and keep your expectations grounded. We work with multiple lenders, and their criteria may differ. That creates options to consider, not a guarantee that any one lender will approve an application or offer particular terms. We don’t provide legal advice about bankruptcy. The focus here is on presenting an honest application.
Submitting applications repeatedly isn’t a reliable shortcut to a better result. Instead, take time to understand your current situation, settle on a vehicle amount that fits your budget, and prepare consistent information before applying. Make sure the application reflects your current details, not an outdated picture. This gives the lender a clear basis for review, while leaving the decision with the lender.
We know credit history can feel personal, and it’s reasonable to have questions about how it may affect your options. Approach the process one step at a time. Be candid about your background, focus on the information you can provide and the budget you can plan for, and consider available financing without treating any application as a sure thing.
Choose a Manageable Vehicle Budget Before Seeking Car Loan Approval
A vehicle budget should reflect more than the amount you hope to borrow. Start with your household obligations and priorities, then consider what payment would leave room for regular expenses, maintenance, and insurance requirements. Beyond basic loan installments, long-term ownership costs can also include security upgrades; for instance, motorists overseas often factor in services like insurance approved vehicle tracker installation UK to keep insurance policies compliant. This gives you a practical way to compare vehicles before choosing one. A budget can guide your application, but it can’t predict a lender’s decision.
Match the vehicle and requested financing to your budget
Consider the total amount you may need to finance, not just the vehicle’s category or features. Compare a lower requested amount with a higher one by asking how each would fit alongside your other commitments. This is a planning exercise, not an approval prediction. It helps you check whether the vehicle you’re considering aligns with your priorities.
Looking across available used vehicles can help you weigh what matters most against your budget. We invite you to explore our available used vehicle inventory as you compare options.
| Budget factor | Lower requested amount | Higher requested amount |
|---|---|---|
| Household obligations | Consider how the request fits alongside recurring bills and other commitments. | Check whether more of your available budget would be dedicated to the vehicle. |
| Vehicle priorities | Decide which needs matter most and where you could be flexible. | Consider whether additional features or preferences are worth the larger request. |
| Room for changes | Think about whether this choice leaves breathing room in your household plan. | Consider how a larger commitment could affect other priorities. |
Use the comparison to clarify your comfort level, not to assume that choosing a lower amount will secure approval. A realistic request is one you can explain in the context of your finances and vehicle needs.
Consider a trade-in as part of your financing plan
If you have a vehicle to trade, its value may affect how much you need to finance toward another purchase. Don’t assume a trade-in value in advance, and remember that a trade-in doesn’t guarantee approval. Treat it as one part of the plan, alongside your vehicle choice and overall budget. You can begin estimating your trade-in value as you plan.
As you compare scenarios, keep the same household priorities in view. If a trade-in changes the amount you expect to finance, revisit your budget rather than automatically moving to a more expensive vehicle. This measured approach can help you decide what request feels manageable, even though the lender makes the financing decision.
As you work out how to improve chances of car loan approval, focus on matching the vehicle and financing request to your real budget. Explore vehicle financing with us as you consider your next step.
How to Apply for Car Financing with Globul Cars in Las Vegas
A prepared application can make the next steps clearer, even though no dealership or lender can promise an approval decision. We’ve been in business since 2013 and work with multiple lenders to help Las Vegas buyers consider available financing options. A straightforward way to begin is to set a vehicle budget, organize your information, submit an application, and review the options available for your situation.
- Identify a manageable budget. Consider your household priorities and the amount you’re comfortable requesting for a vehicle.
- Prepare your information. Gather accurate personal, income, and identification details so you can complete the application carefully.
- Submit the application. Review your answers for accuracy before sending them for consideration.
- Review available options. Lenders make financing decisions. Consider any options presented in light of your needs and budget.
What applicants can expect from a multiple-lender approach
We work with multiple lenders and offer flexible financing options for first-time buyers, people with no credit, challenging credit, or rebuilding credit, and applicants with open bankruptcy or bankruptcy in their history, including Chapter 7 and Chapter 13. Each lender reviews the application and makes its own decision, so options and outcomes can vary. We don’t offer in-house financing, and we can’t guarantee approval or specific terms.
This approach gives applicants with different backgrounds options to consider without treating any one credit circumstance as an automatic answer. Share your situation accurately and review available financing in relation to the vehicle and budget you have in mind. Take time to understand the details before deciding how you want to proceed.
Take the next step with a prepared application
Before starting, make sure your application information is accurate and that you can clearly describe your income and identification details. We accept all types of income, including cash, 1099, W-2, trust income, and more. We accept every form of ID, including passports and international IDs. Careful preparation helps you submit a clear picture, though the lender still determines the financing decision.
Our online financing application is a practical next step when you’re ready to share your information for consideration. Review your answers before submitting, and keep your vehicle budget in mind as you consider any options that follow. If you’re ready to explore the process, explore financing with Globul Cars.
There’s no guaranteed formula for how to improve chances of car loan approval. A realistic budget, an accurate application, and a clear understanding of available options can help you approach the process with confidence while keeping expectations grounded. We’re here to make financing easier to understand as you consider your next vehicle in Las Vegas.
Move Forward With a Plan That Fits Your Life
Applying for a car loan is one step in a larger decision: choosing a vehicle and financing arrangement that still makes sense after the excitement of buying has passed. As you move forward, consider how your needs could change and whether your plans leave room for other priorities. That perspective keeps the question of how to improve chances of car loan approval connected to what matters most: making a thoughtful choice for your circumstances.
You don’t need every answer before exploring your options. Start with the vehicle and budget you have in mind, then take time to understand any financing option presented before deciding what works for you. Approval isn’t guaranteed, but a clear-eyed approach can help you make your next move with greater confidence.
Explore car financing with Globul Cars and take the next step at a pace that feels right. We’re glad to help you consider your options in Las Vegas.
Frequently Asked Questions
Can I get a car loan with no credit history?
You can apply without an established credit history, but approval isn’t guaranteed. If you’re a first-time buyer, explain your situation accurately rather than trying to make your credit background sound different. A lender may consider the application as a whole, including the vehicle amount requested and other financial information. We offer flexible financing options for buyers with no credit, but each lender makes its own decision.
Does applying for a car loan hurt your credit score?
A car financing application may involve a credit inquiry, which can affect your score. The effect can vary, and the inquiry is only one part of your credit picture. Before submitting an application, understand what information you’re providing and whether a credit check is part of the process. Avoid applying impulsively. First narrow down your budget and make sure the details you enter are accurate.
Can I get approved for a car loan after bankruptcy?
Possibly, but a bankruptcy in your history doesn’t guarantee approval or automatically determine the outcome. Lenders review each application and make their own financing decisions. If bankruptcy is part of your circumstances, be candid and provide accurate information. We offer flexible financing options for applicants with open bankruptcy or bankruptcy in their past, including Chapter 7 and Chapter 13. Outcomes depend on lender review.
What income documents do I need to apply for a car loan?
There isn’t one document list that applies to every applicant or income situation. Be ready to explain how you earn income and provide accurate details that reflect it. Employment, contract work, cash income, and trust income may each be described differently. We accept W-2, 1099, trust income, cash income, and other income types. Prepare relevant information, but don’t assume a particular document is required in every case.
Can I use cash income when applying for car financing?
Yes, we accept cash income. Describe it honestly and consistently in your application, and be prepared to explain how it fits your overall income picture. Don’t estimate or present figures as more certain than they are. The lender makes the financing decision based on the application and its review, so accepting cash income doesn’t guarantee approval or particular terms.
Does a larger down payment guarantee car loan approval?
No. A larger down payment doesn’t guarantee approval. It may reduce the amount you’re asking to finance, but the lender still reviews the complete application and makes the decision. Before setting aside money for a down payment, consider your household needs and leave room in your budget for other priorities. Treat the amount as one planning factor, not a promise of a lending outcome.
Can I get a car loan without a cosigner?
You can submit an application without a cosigner, but whether financing is approved depends on the lender’s review. A cosigner isn’t a guarantee of approval either. Before applying, make sure your personal and financial details are accurate and that the vehicle amount fits your budget. We work with multiple lenders, but each lender decides whether an application meets its criteria.


