
Having no credit history can feel like a roadblock when you’re ready to buy a car, but a blank or thin credit file is different from a history of missed payments. If you’re wondering how to get a car loan with no credit history, your income, expenses, identification, and vehicle choice can all help provide context for your application.
We’ll explain what lenders may consider, how to prepare useful financial details, and how to compare possible financing paths, including applying on your own, considering a co-signer, or making a down payment. At Globul Cars, we’ve been in business since 2013 and work with multiple lenders. We don’t offer in-house financing. We provide flexible financing options for first-time buyers and people with no credit, challenging credit, rebuilding credit, open bankruptcy, or after bankruptcy, including Chapter 7 and Chapter 13. We accept all types of income, including cash, 1099, W-2, trust income, and more. We also accept every form of ID, including passports and international IDs. If you’re exploring used cars in Las Vegas, we can discuss your needs and help you consider vehicle options that fit your budget. Each lender makes its own decision.
Key Takeaways
- Learn how to get a car loan with no credit history by understanding how limited borrowing history differs from a record of missed payments.
- Prepare a clearer application by organizing your financial details and setting a vehicle budget that accounts for regular expenses.
- Compare applying on your own, involving a co-signer, and making a down payment, including the benefits and trade-offs of each option.
- Follow a practical application sequence and learn how we help Las Vegas buyers explore financing options without promising a lender decision.
Can you get a car loan with no credit history?
It’s reasonable to have questions about a first car loan when there’s little or no borrowing history for a lender to review. Financing may be possible, but no credit history does not guarantee approval. A negative credit history does not automatically determine the outcome either. Lenders assess the full application, and their criteria can differ.
No credit history means there’s limited information about past borrowing; bad credit generally means there’s negative information in a credit history, such as missed payments. A blank or thin file doesn’t show that someone has failed to repay a loan. It means there’s less past credit activity for a lender to assess.
No credit history versus bad credit
With no established credit, you may have few or no loan or credit-card accounts showing how you handled payments. With negative credit history, a file may include past payment problems or other adverse information. These are different situations, but neither one guarantees a particular lending decision.
A lender may assess an applicant with little credit information differently from someone with a longer history that includes missed payments. In either case, the lender considers the application as a whole. So the useful question isn’t only whether you have a credit score. It’s also what information about your income, expenses, and vehicle choice helps describe your circumstances.
For a general overview of vehicle borrowing, Car finance describes direct and indirect financing. Understanding the basic routes can make the process less unfamiliar, though the financing method doesn’t replace the lender’s assessment of your application.
What lenders may consider beyond a credit record
When credit information is limited, a lender may review other details in the application. These aren’t universal requirements, and lenders may weigh them differently. They can help provide context when there’s little borrowing history to consider.
- Income: The amount and consistency of your income may help show how a proposed payment fits into your finances.
- Employment: Work history can provide context about your current income situation.
- Monthly obligations: Regular bills and debt payments affect how much room remains in your budget.
- The vehicle: The car and its price are part of the financing request, so the vehicle you choose matters to the application.
For example, an applicant with limited credit history, steady income, and manageable monthly obligations presents a different overall picture from someone whose budget is already stretched. That example doesn’t predict a lender’s decision. It illustrates why details beyond credit can matter.
So, how to get a car loan with no credit history starts with looking at the whole application rather than assuming a missing credit record tells the complete story. The next step is to organize your financial information and set a manageable budget before applying.
How to prepare for a car loan application without credit
Preparation makes a financing conversation more focused, even though no checklist guarantees a lender’s decision. Before choosing a vehicle, write down your income, regular expenses, and the payment range you believe you can manage. Gather information that accurately describes your circumstances. Lenders assess applications differently, so use these steps to prepare a clear picture, not as a universal list of requirements.
Organize income and identity information
Collect current information about your income and identification before you begin. The records that best describe your situation can depend on how you earn and the identification you use. If you have several income sources, list each one and how often you receive it. Keep the details consistent, and use your records rather than estimates when possible.
Also note regular financial commitments, such as housing, utilities, insurance, and existing debt payments. This gives you a clearer view of how a possible vehicle payment could fit into your monthly budget. The Consumer Financial Protection Bureau’s auto-loan guidance offers general information about the process and questions buyers may want to consider. Our guide, Accessible Vehicle Financing Solutions in Las Vegas: Your Guide to All-Credit Approvals, offers additional context for people exploring financing.
- Write down your income sources and how frequently you receive income.
- List recurring expenses and existing financial commitments.
- Gather identification and records that help explain your circumstances.
- Estimate a payment range that leaves room for your other regular expenses.
Use this as a personal preparation aid, not as a list of documents every lender will require. Clear, accurate information helps keep the discussion useful and grounded in your actual circumstances.
Set a realistic vehicle and payment budget
Start with your monthly budget, not the vehicle’s advertised price or a payment estimate on its own. Account for recurring bills and day-to-day expenses, then decide what you could set aside without relying on an unusually favorable month. Vehicle ownership can also involve costs beyond a loan payment, including insurance, fuel, and maintenance.
The vehicle you choose, the loan term, and the lender’s assessment can all affect payment details. Think about what you need the car to do, then set a practical price range before comparing vehicles. Browse our used-car inventory with those priorities in mind, focusing on options that suit your needs and budget.
If you’re learning how to get a car loan with no credit history, let your budget and circumstances guide the conversation rather than trying to fit a generic checklist. Explore financing options with us and tell us what you need from a vehicle.
Co-signer, down payment, or applying on your own: compare your options
A co-signer isn’t automatically required to explore car financing without an established credit history. Depending on your circumstances, you can consider applying on your own, involving a co-signer, or making a down payment. Each option has possible benefits and trade-offs, and lender criteria and available terms vary. None guarantees approval or a particular rate.
Use this comparison to weigh what each option involves before deciding which path to discuss:
| Option | Potential benefit | Trade-off to consider |
|---|---|---|
| Apply on your own | Your application reflects your own income, obligations, and circumstances. | With little credit information, a lender may have less borrowing history to assess. The decision and terms depend on the full application. |
| Consider a co-signer | A co-signer adds another person’s financial profile for the lender to consider. | The co-signer may take on responsibility under the loan agreement, so the arrangement can affect both people. |
| Make a down payment | A down payment reduces the amount you need to finance. | Using money upfront can leave less available for other expenses, and it doesn’t guarantee approval or specific terms. |
When a co-signer could be part of the conversation
A co-signer may be worth discussing if someone you trust is willing to have their financial profile considered alongside yours. Before applying together, talk openly about the responsibility involved, how payments would be handled, and what could happen if payments become difficult. Make sure everyone understands the loan agreement before deciding. A co-signer is one option, not a requirement for every buyer.
How a down payment and vehicle choice affect the application
A down payment can lower the amount financed, but deciding how much to put down means balancing the purchase with your other financial needs. One fixed amount won’t suit every buyer or lender. Leave room in your budget for regular obligations and the ongoing costs of owning a vehicle.
The vehicle matters, too. Choosing a car that fits your day-to-day needs and budget can keep the financing discussion focused on what you can manage. Compare options based on practical needs, not only the listed price or a hoped-for payment. We offer used cars, and you can browse our used-car inventory as you consider which vehicles fit your plans.
As you weigh how to get a car loan with no credit history, focus on the option that makes sense for your finances rather than treating a co-signer or down payment as essential. We work with multiple lenders and can discuss your circumstances and financing options. The lender makes the decision on your application.
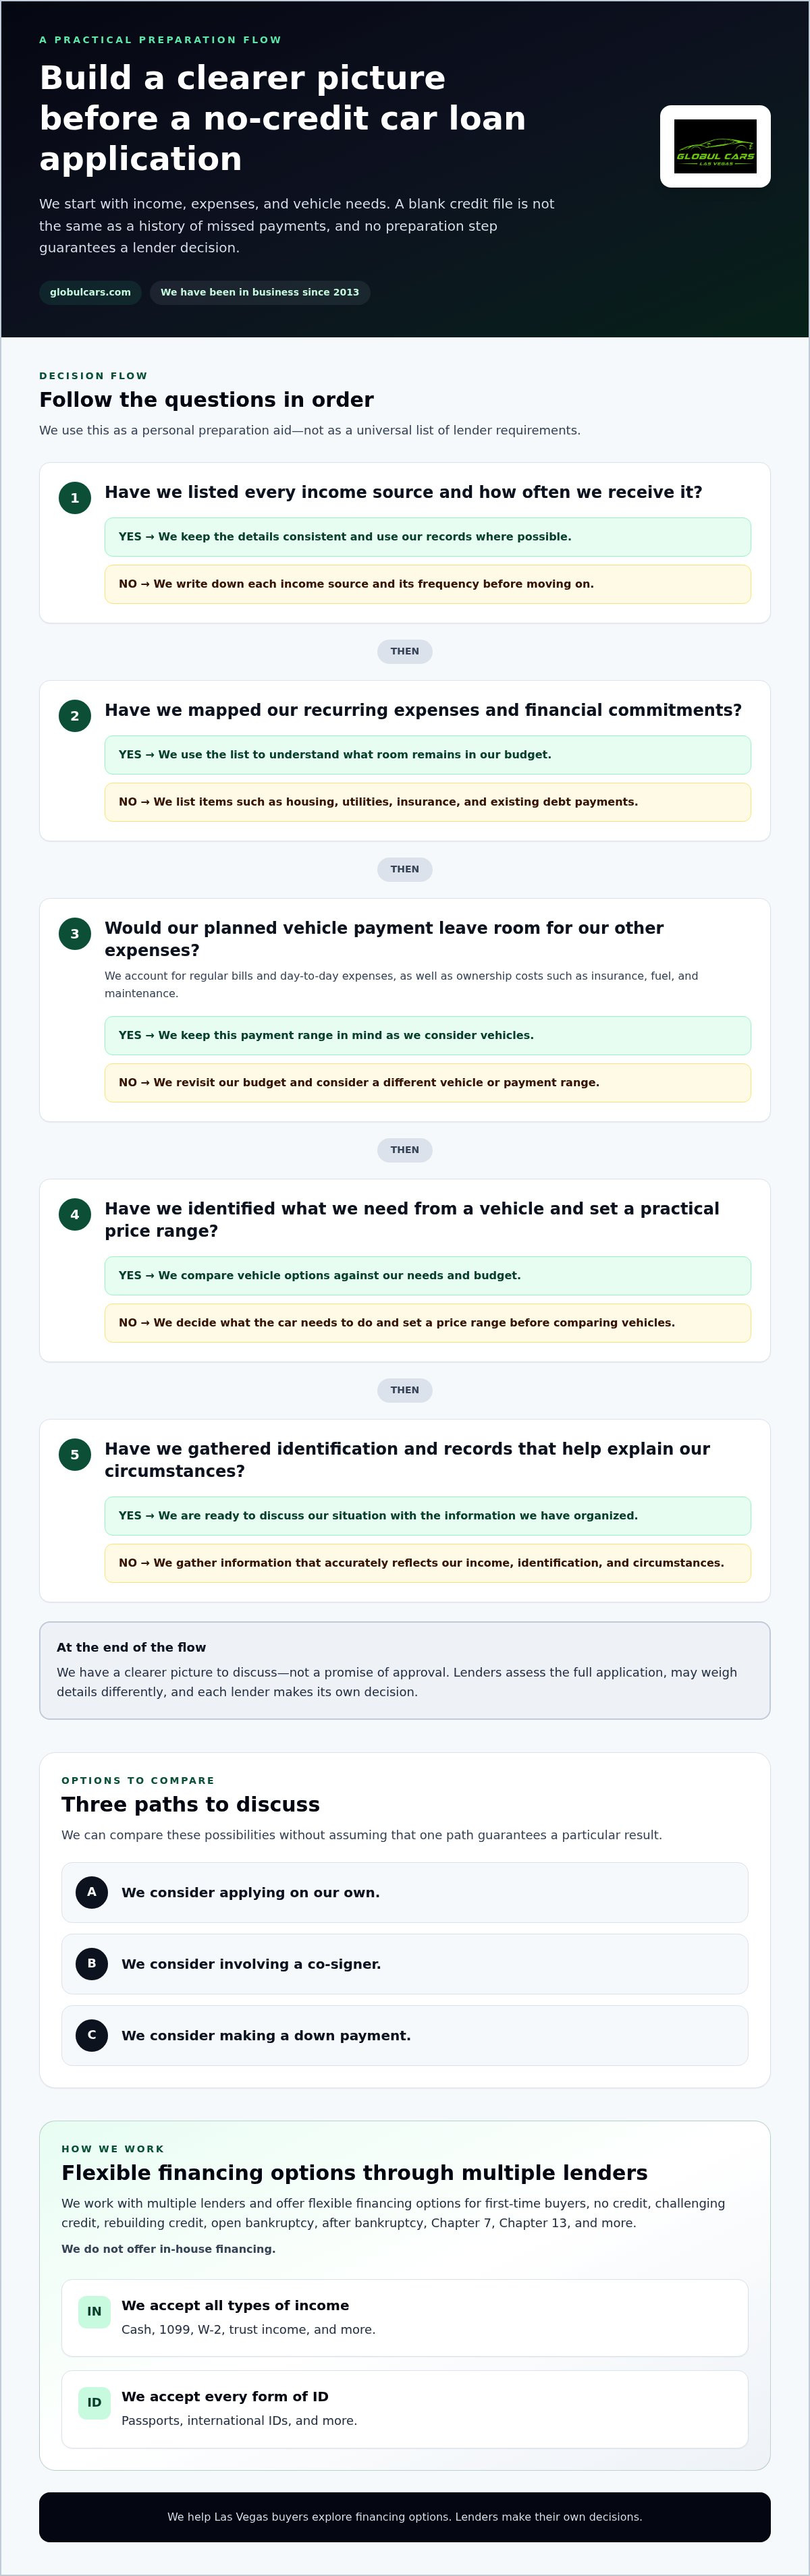
How to apply for a car loan with no credit history
A clear sequence can make the application process easier to manage. Rather than trying to predict a lender’s decision, focus on sharing accurate information, understanding the financing details presented, and choosing a vehicle and payment plan that fit your circumstances.
- Set a workable budget. Review your regular income and expenses, then decide what payment range leaves room for other needs. Consider the overall cost of owning a vehicle, not just the monthly loan payment.
- Identify the vehicle you need. Think about how you’ll use the car and which practical features matter to you. A realistic vehicle choice gives the financing conversation a useful starting point.
- Gather relevant information. Prepare current details about your income, identification, and financial obligations. What’s useful can vary with your income and individual circumstances, so treat this as preparation rather than a universal document checklist.
- Complete the application accurately. Share truthful, consistent information about your income, identity, and finances. If something has changed or needs context, explain it clearly instead of guessing or leaving out relevant details.
- Discuss financing options. Talk through your situation and vehicle needs with us. We work with multiple lenders and can help make the discussion practical, without promising approval or a particular decision. You can also begin by completing our online financing application.
- Review the proposed terms before deciding. Take time to understand the payment, loan term, and total amount financed when those details are provided. Consider how the full arrangement fits your budget, not only whether one monthly figure looks manageable.
Review financing details before making a decision
A monthly payment is only one part of a financing proposal. The loan term shows how long payments are scheduled to continue, while the total amount financed describes the amount being borrowed. Review these details together with any other terms presented so you can understand the overall commitment.
If a term or figure isn’t clear, ask for an explanation in plain language before moving forward. Compare the proposal with your budget and consider whether the payment remains manageable alongside your regular expenses. Don’t let urgency or one attractive-looking number make the decision for you. A longer term, for example, changes how long you’ll be making payments, so review the complete schedule rather than focusing only on the monthly amount.
Understanding how to get a car loan with no credit history means approaching each step carefully, from the first budget estimate to reviewing the proposed terms. We’re here to discuss your vehicle needs and financing options in a straightforward way. Start a financing conversation with us.
How we help Las Vegas buyers explore financing with no credit
Vehicle financing can start with a straightforward conversation about what you need from a car and what fits your budget. We work with multiple lenders and help Las Vegas buyers explore financing options alongside used-car choices for practical transportation. We don’t offer in-house financing. Each lender reviews the application and makes its own decision, so we don’t promise approval or specific terms.
Tell us what you’re looking for and what payment range you’re comfortable considering. That gives the conversation a practical focus: finding vehicles that suit your needs and discussing possible financing next steps based on your circumstances.
Income and identification options we accept
We accept all types of income, including cash, 1099, W-2, trust income, and more. We also accept every form of ID, including passports and international IDs. Share accurate details about your income and identification so the application reflects your circumstances. The lender reviews the application and makes the financing decision.
If you’re unsure how to explain part of your situation, bring it up during the financing discussion. A clear account helps us understand your needs and discuss how your vehicle preferences and budget fit into the options being explored.
Financing situations we work with
We offer flexible financing options for first-time buyers and people with no credit, challenging credit, or rebuilding credit. We also work with buyers with open bankruptcy or after bankruptcy, including Chapter 7 and Chapter 13. The starting point is your individual application and the vehicle you’re considering. We can discuss practical used-car choices alongside financing possibilities, while the lender makes its own decision.
Choosing a vehicle with your everyday needs and budget in mind can make the next steps more manageable. Browse our used-car inventory as you consider what could work for your plans. We can discuss your situation and help you explore financing options in Las Vegas, with the conversation focused on your needs.
Take the next step at your own pace
Your first car purchase can also be the start of building a borrowing history. You don’t need to have every detail figured out before exploring options. Start with a clear sense of what you need from a vehicle and what fits your budget, then use the financing conversation to understand possible next steps. Taking time to make a considered decision matters more than rushing to choose.
If you’re still considering how to get a car loan with no credit history, we’re ready to discuss your circumstances and help you explore vehicle financing options in Las Vegas. We’ll listen to what you’re looking for and keep the conversation focused on your needs, because the right next step depends on your situation.
Talk with us about your financing options. Start with a conversation about your budget, vehicle needs, and financing situation.
Frequently Asked Questions
Can I get a car loan with no credit history and no co-signer?
You can explore financing without a co-signer, but applying on your own doesn’t guarantee approval. A lender reviews your full application, and its criteria may differ from another lender’s. Before discussing options, prepare a realistic budget and clear information about your finances. We work with multiple lenders and can discuss your circumstances and vehicle needs in Las Vegas, then help you explore possible next steps.
Does applying for a car loan affect my credit score?
The effect can depend on whether a credit check is made and how it’s handled. Don’t assume every inquiry or application has the same impact. Before proceeding, understand what information you’re authorizing and whether the application involves a credit check. If a term or permission is unfamiliar, ask for a clear explanation before deciding. That way, you can make an informed choice about moving forward.
How much of a down payment do I need if I have no credit?
There isn’t one down payment amount that applies to every buyer or lender. The vehicle, amount financed, your budget, and the lender’s assessment can all shape the discussion. Consider what you could contribute while still covering regular expenses and keeping room for other needs. A down payment may reduce the amount financed, but it doesn’t guarantee approval or a particular payment or loan term.
Can I get a car loan if I earn cash or work as a 1099 contractor?
Your income source alone doesn’t determine whether a lender will approve an application. The lender considers the full picture, and its criteria can vary. Be ready to explain how you earn, how often you receive income, and any changes that affect your current finances. We accept all types of income, including cash, 1099, W-2, trust income, and more, and can discuss your vehicle needs. The lender makes the financing decision.
Can someone new to the United States apply for a car loan without a credit history?
A limited U.S. credit record doesn’t explain your full financial circumstances, but a lender decides based on its assessment of the application. Be prepared to describe your income, budget, and vehicle needs clearly. We accept every form of ID, including passports and international IDs, and can discuss your situation as part of the financing conversation. Lender requirements and decisions can differ.
What happens if a lender does not approve my car loan application?
A declined application reflects that lender’s assessment; it doesn’t mean another lender will approve a later application. If possible, ask which parts of the application affected the decision. Then consider whether adjusting your vehicle choice or budget could make the request more manageable. We can discuss your circumstances and other options to explore, while being clear that each lender makes its own decision.


