
What if the monthly payment that looks manageable in a calculator still puts pressure on the rest of your budget? A car loan calculator can help you estimate a payment, but the result depends on the figures you enter, including the amount financed, APR, and loan term.
Before discussing financing, it helps to know which inputs shape the estimate and how changing them affects the result. This guide explains how to compare scenarios, check the assumptions behind a calculator’s output, and weigh the payment against your overall budget. Whether you’re considering a used car, truck, or pickup in Las Vegas, remember that a calculator estimate is not an approval or a promise of specific loan terms.
Globul Cars is a Las Vegas used car dealership offering pre-owned vehicles and financing options for customers with different credit backgrounds, including all credit types and low income. The inventory includes cars, trucks, pickups, and luxury vehicles such as Mercedes-Benz, BMW, Land Rover, Porsche, and Audi.
Key Takeaways
- Use a car loan calculator to estimate a possible payment, then check which assumptions the result depends on.
- Enter a realistic down payment and trade-in amount only when they apply, and adjust one loan factor at a time to compare scenarios.
- APR and loan term affect the estimate, so consider more than the monthly payment when comparing options.
- Account for insurance, fuel, maintenance, registration, and existing monthly obligations before deciding whether a payment fits your budget.
- Save your estimate and its assumptions. A calculator result is not a loan approval or a promise of final terms.
What a Car Loan Calculator Estimates, and What It Leaves Out
A car loan calculator estimates a periodic payment, usually monthly, from the figures you enter. It can help you compare possible financing scenarios, but its output is only as useful as the assumptions behind it. Most calculators use the amount borrowed, the cost of borrowing, and the time allowed for repayment.
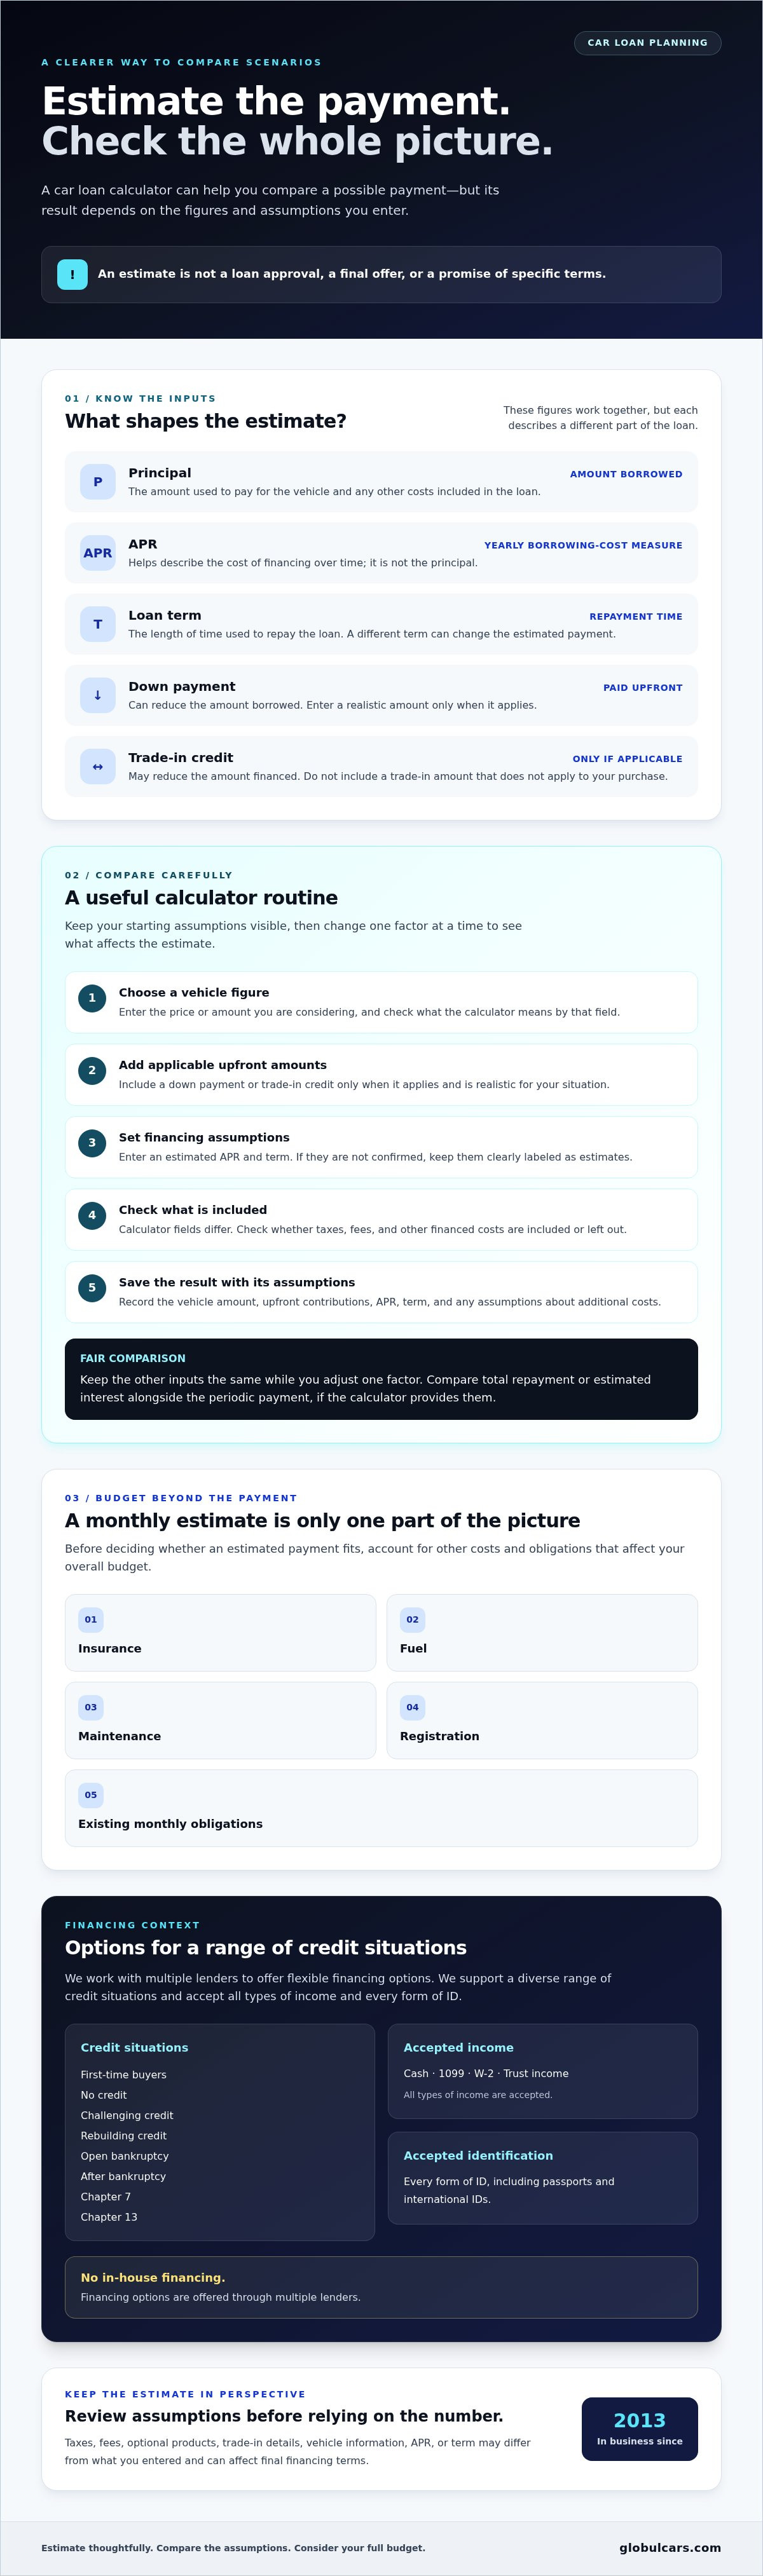
- Principal: The amount borrowed to pay for the vehicle and any other costs included in the loan.
- Interest: The cost of borrowing the principal.
- APR: A yearly measure of borrowing cost. It is not the principal; it helps describe the cost of financing over time.
- Loan term: The length of time used to repay the loan.
- Down payment: Money paid upfront that can reduce the amount borrowed.
These figures are connected, but they are not interchangeable. A calculator uses them to estimate repayment over the selected term. For background on the payment formula, see this explanation of an amortization calculator.
Which figures does a car loan calculator use?
Start with the vehicle amount you want to consider. Enter a down payment and trade-in credit only if they apply to your purchase, since both may reduce the amount financed. That amount becomes the principal used in the estimate. Then enter an APR and loan term. Calculator fields differ, so check whether taxes and fees are included or left out.
Why can the final payment differ from the estimate?
The figures you enter may not match the final financing terms. Taxes, fees, optional products, trade-in details, and final vehicle information can change the amount financed. The APR or term used for the estimate may also differ from the terms ultimately offered. Review the assumptions before using the result as a planning figure.
A calculator provides an estimate, not a loan commitment. It is not a lender approval, final offer, or guaranteed payment.
If you are comparing pre-owned vehicles in Las Vegas, you can use an estimate to narrow your options before discussing financing. Globul Cars offers used cars, trucks, pickups, and pre-owned luxury vehicles, with financing options for customers across credit types and income levels.
How to Use a Car Loan Calculator Step by Step
A car loan calculator is most useful when its inputs reflect the vehicle and financing scenario you are considering. Treat an unconfirmed APR or loan term as an estimate, and record your inputs so you can compare results fairly.
Enter the vehicle and loan assumptions
Begin with the vehicle amount you want to use. Add a realistic down payment and any trade-in credit, but only if each applies to your situation. Check the calculator’s fields: some include taxes, fees, or other financed costs, while others leave them out. Unless a lender has confirmed the APR and term, treat both as assumptions rather than settled terms.
Run scenarios and compare the results
Use these steps to make your comparisons more useful:
- Choose a vehicle figure. Enter the price or amount you are considering, and check what the calculator means by that field.
- Enter upfront contributions. Add a down payment and trade-in credit only when applicable. Do not enter amounts you cannot realistically put toward the purchase.
- Set the financing assumptions. Enter an estimated APR and term. If neither is confirmed, label them as estimates in your notes.
- Check what is included. Find out whether taxes, fees, and other financed amounts are part of the calculation. If they are not, the displayed payment may not reflect the full amount financed.
- Save the result. Record the payment estimate alongside the vehicle amount, down payment, trade-in credit, APR, term, and any assumptions about additional costs.
Compare scenarios by changing one input at a time. For example, keep the vehicle amount, APR, and down payment the same while adjusting the term. Then return to your starting assumptions and change only the down payment. This makes it easier to identify which change affected the estimated payment.
If the calculator shows total repayment or estimated interest, review those figures beside the periodic payment. A lower monthly amount alone does not show the full cost over the loan term. Keep your results together, and use the used-auto sales buyer’s guide for broader context as you consider a vehicle.
For more background on the financing process, the Consumer Financial Protection Bureau offers guidance on getting an auto loan. Once you have reviewed your estimate and budget, bring your questions to a financing conversation. Globul Cars offers vehicle financing options for buyers with different credit backgrounds in Las Vegas.
How APR, Loan Term, and Down Payment Change the Estimate
A car loan estimate depends on several inputs working together. Change one assumption at a time while keeping the others consistent, so you can see how each affects the result. The comparisons below describe general effects, not a quote or a prediction of specific loan terms.
| Assumption changed | Example comparison | Possible effect on estimate |
|---|---|---|
| APR | Use a lower or higher estimated APR; leave the other inputs unchanged. | A higher APR generally increases the estimated payment and borrowing cost. |
| Loan term | Compare a shorter term with a longer one, keeping the amount financed and APR the same. | A longer term can lower each periodic payment, but extends repayment and can increase total interest. |
| Down payment | Compare the current down payment with a larger amount, keeping other assumptions unchanged. | A larger down payment generally reduces the amount financed and may lower the estimated payment. |
How does APR affect an estimated car payment?
APR is the borrowing-cost assumption entered in the calculator. If the amount financed and term stay the same, a higher APR usually raises the estimated payment because borrowing costs more. Treat an APR you enter as an assumption until financing terms are confirmed. APR is not a credit score, and a credit score alone does not guarantee a particular APR or approval.
How do loan term and down payment affect the result?
A longer term spreads repayment over more time, which can lower the periodic payment while keeping the debt in place longer. Depending on the loan’s terms, paying over more time can also mean more total interest. A larger down payment, with other factors unchanged, reduces the amount financed and can lower the estimated payment and borrowing cost. Compare total repayment and interest, not only the monthly figure.
APR, amount financed, and loan term jointly shape a payment estimate. Use the table as a guide, then test each adjustment separately to see what changed. The result remains an estimate, not a lender’s approval or guaranteed terms.
When exploring financing for a pre-owned vehicle in Las Vegas, consider the payment estimate alongside the vehicle itself and your budget. Globul Cars offers financing options for buyers with all credit types, as well as pre-owned cars, trucks, pickups, and luxury vehicles.
How to Check Whether the Estimated Payment Fits Your Budget
A loan payment that looks manageable does not automatically mean the vehicle is affordable for your household. A car loan calculator estimates a payment from the figures entered, but it cannot account for your full financial picture or decide how much room you need for other expenses. Treat the estimate as one part of your budget check.
What costs should you consider beyond the loan payment?
List the estimated loan payment separately from the other costs of owning and using a vehicle. Consider:
- Insurance
- Fuel
- Maintenance
- Registration
- Existing monthly obligations, such as housing, utilities, and other bills
Use your own insurance quotes, recent fuel and maintenance records, and current budget rather than generic cost assumptions. Expenses can vary with the vehicle, how you use it, and your personal circumstances, so leave room for costs that may change. The goal is to understand the full monthly commitment, not just the loan payment.
Before reviewing vehicle inventory or discussing financing, write down a payment range that feels manageable after accounting for those other expenses. Compare calculator scenarios against that range. If you are shopping in Las Vegas, consider the specific type of vehicle you need, such as a car, truck, or pickup, as part of your comparison. For an example of how pre-owned vehicle ownership and running costs are evaluated in comprehensive buyer guides, you can learn more about Carz World Pte Ltd. A calculator can help you explore options, but it cannot assess your household’s complete finances or tell you what you can comfortably afford.
Does a calculator tell you whether you will be approved?
No. A calculator estimates payments based on assumptions; it does not determine eligibility or provide lender approval. Lenders assess applications using their own processes and the information available to them, so final terms may differ from an estimate. For more background, read our Las Vegas vehicle financing guide.
Globul Cars offers vehicle financing options for customers with different credit backgrounds, including all credit types and low income. After reviewing your budget, you can explore financing options.
What to Do After Using a Car Loan Calculator
Use your estimate as a starting point for a financing conversation, not as a final answer. Before taking the next step, work through this checklist:
- Keep the estimate: Save the payment and the figures you entered.
- Confirm the assumptions: Check the vehicle amount, down payment, trade-in credit, APR, term, and any costs included.
- Review your budget: Consider the payment alongside ownership costs and your other monthly obligations.
- Prepare questions: Ask which terms and information apply to your situation.
A calculator cannot confirm approval or guarantee a lender’s final payment. Your saved estimate can help explain what you are considering, but the financing provider’s review determines which options may be available.
What information can help you discuss financing?
Ask the dealership or financing provider what information they need, since requirements and review processes can differ. Before beginning a financing discussion at Globul Cars, confirm what you should bring or provide.
Can buyers with different credit histories ask about options?
Yes. Globul Cars offers financing options for buyers with all credit types, including people with limited or challenging credit backgrounds, and for customers with low income. These circumstances do not guarantee approval or particular terms, so discuss your situation with the financing provider.
After considering your estimate and budget, you can ask about vehicle financing options and clarify what may fit your situation. A calculator result is not an approval or a promise of specific loan terms.
When you are ready to take the next step, you can explore vehicle financing options. Starting there does not guarantee approval; use it to begin asking questions and confirm what information is needed.
Use Your Estimate to Plan Your Next Step
A car loan calculator helps you explore possible payments, but the estimate depends on the figures you enter and is not a lender’s approval or final offer. Compare APR, loan term, and down payment assumptions, then consider the payment alongside insurance, fuel, maintenance, registration, and your other monthly obligations. A payment that looks manageable on its own may not fit your full budget.
When you are ready to discuss financing in Las Vegas, Globul Cars offers financing options for customers with all credit types and low income. Its inventory includes used cars, trucks, pickups, and pre-owned luxury vehicles. Financing terms are not guaranteed.
Explore vehicle financing options when you are ready. Take your time, ask questions, and move forward with a clearer sense of what fits your budget.
Frequently Asked Questions
How does a car loan calculator work?
A car loan calculator uses the figures you enter, such as the amount financed, estimated APR, and loan term, to estimate a periodic payment. Some calculators also show estimated total interest or total repayment. Results depend on your assumptions and the calculator’s fields, so check whether taxes, fees, or other financed amounts are included. Use the result for planning, not as a lender offer, approval, or guaranteed payment.
What information do I need for a car loan calculator?
You generally need an estimated vehicle amount, a down payment, a loan term, and an APR assumption. Add a trade-in credit if it applies, and check whether the calculator asks for taxes or fees. You can use estimated figures to compare scenarios, but label them clearly. If a lender has not confirmed the APR or term, treat those entries as assumptions, not guaranteed financing terms.
Does a car loan calculator affect my credit score?
Using a calculator by itself is an estimate exercise, not a loan application. A separate application or lender process may involve steps that could affect your credit, depending on how that process works. Before submitting personal or financial information, ask the lender or dealership what the next step involves. Do not assume a calculator, prequalification, and formal application have the same effect on your credit.
Can I use a car loan calculator before I know my APR?
Yes. Enter a clearly labelled APR estimate to explore how different assumptions may change the payment. Compare one scenario at a time while keeping the other inputs consistent. The result can help with planning, but it cannot predict the APR a lender will offer. Once you receive confirmed financing terms, update the calculator and review the estimated payment alongside total repayment and interest, if shown.
Why is my car loan calculator payment different from a lender’s estimate?
The figures or calculation fields may differ. A lender’s estimate could use a different amount financed, APR, loan term, down payment, trade-in value, taxes, fees, or other included items. Compare the assumptions one by one, and ask the lender what its estimate covers. Until financing terms are confirmed, treat the calculator result as a planning estimate rather than a promise of the final payment.
Does a lower monthly payment mean a car loan costs less?
Not necessarily. A lower payment may reflect a longer repayment term, which can extend the time you are paying interest. Compare the amount financed, APR, term, total repayment, and costs included, rather than focusing on one monthly figure. A calculator can illustrate how assumptions affect the estimate, but your budget and confirmed financing terms should guide your decision. Make room for vehicle expenses beyond the loan payment, too.
Can I get financing if I have no credit or challenging credit?
You can ask about options, but a calculator cannot determine approval or specific terms. Globul Cars in Las Vegas offers financing options for customers with all credit types, including buyers with no credit or challenging credit, and for customers with low income. Approval and terms are not guaranteed. Discuss your circumstances with the financing provider.


